Rivelle vs Pinery Residences: EC vs private condo in Tampines West
Written by Jeffery Ng · Published · 6 min read
Rivelle and Pinery Residences are a few hundred metres apart and serve the same MRT station. One is an executive condominium with eligibility rules and a minimum occupation period; the other is a private condo above a mall. This article works through what the gap between them actually buys.
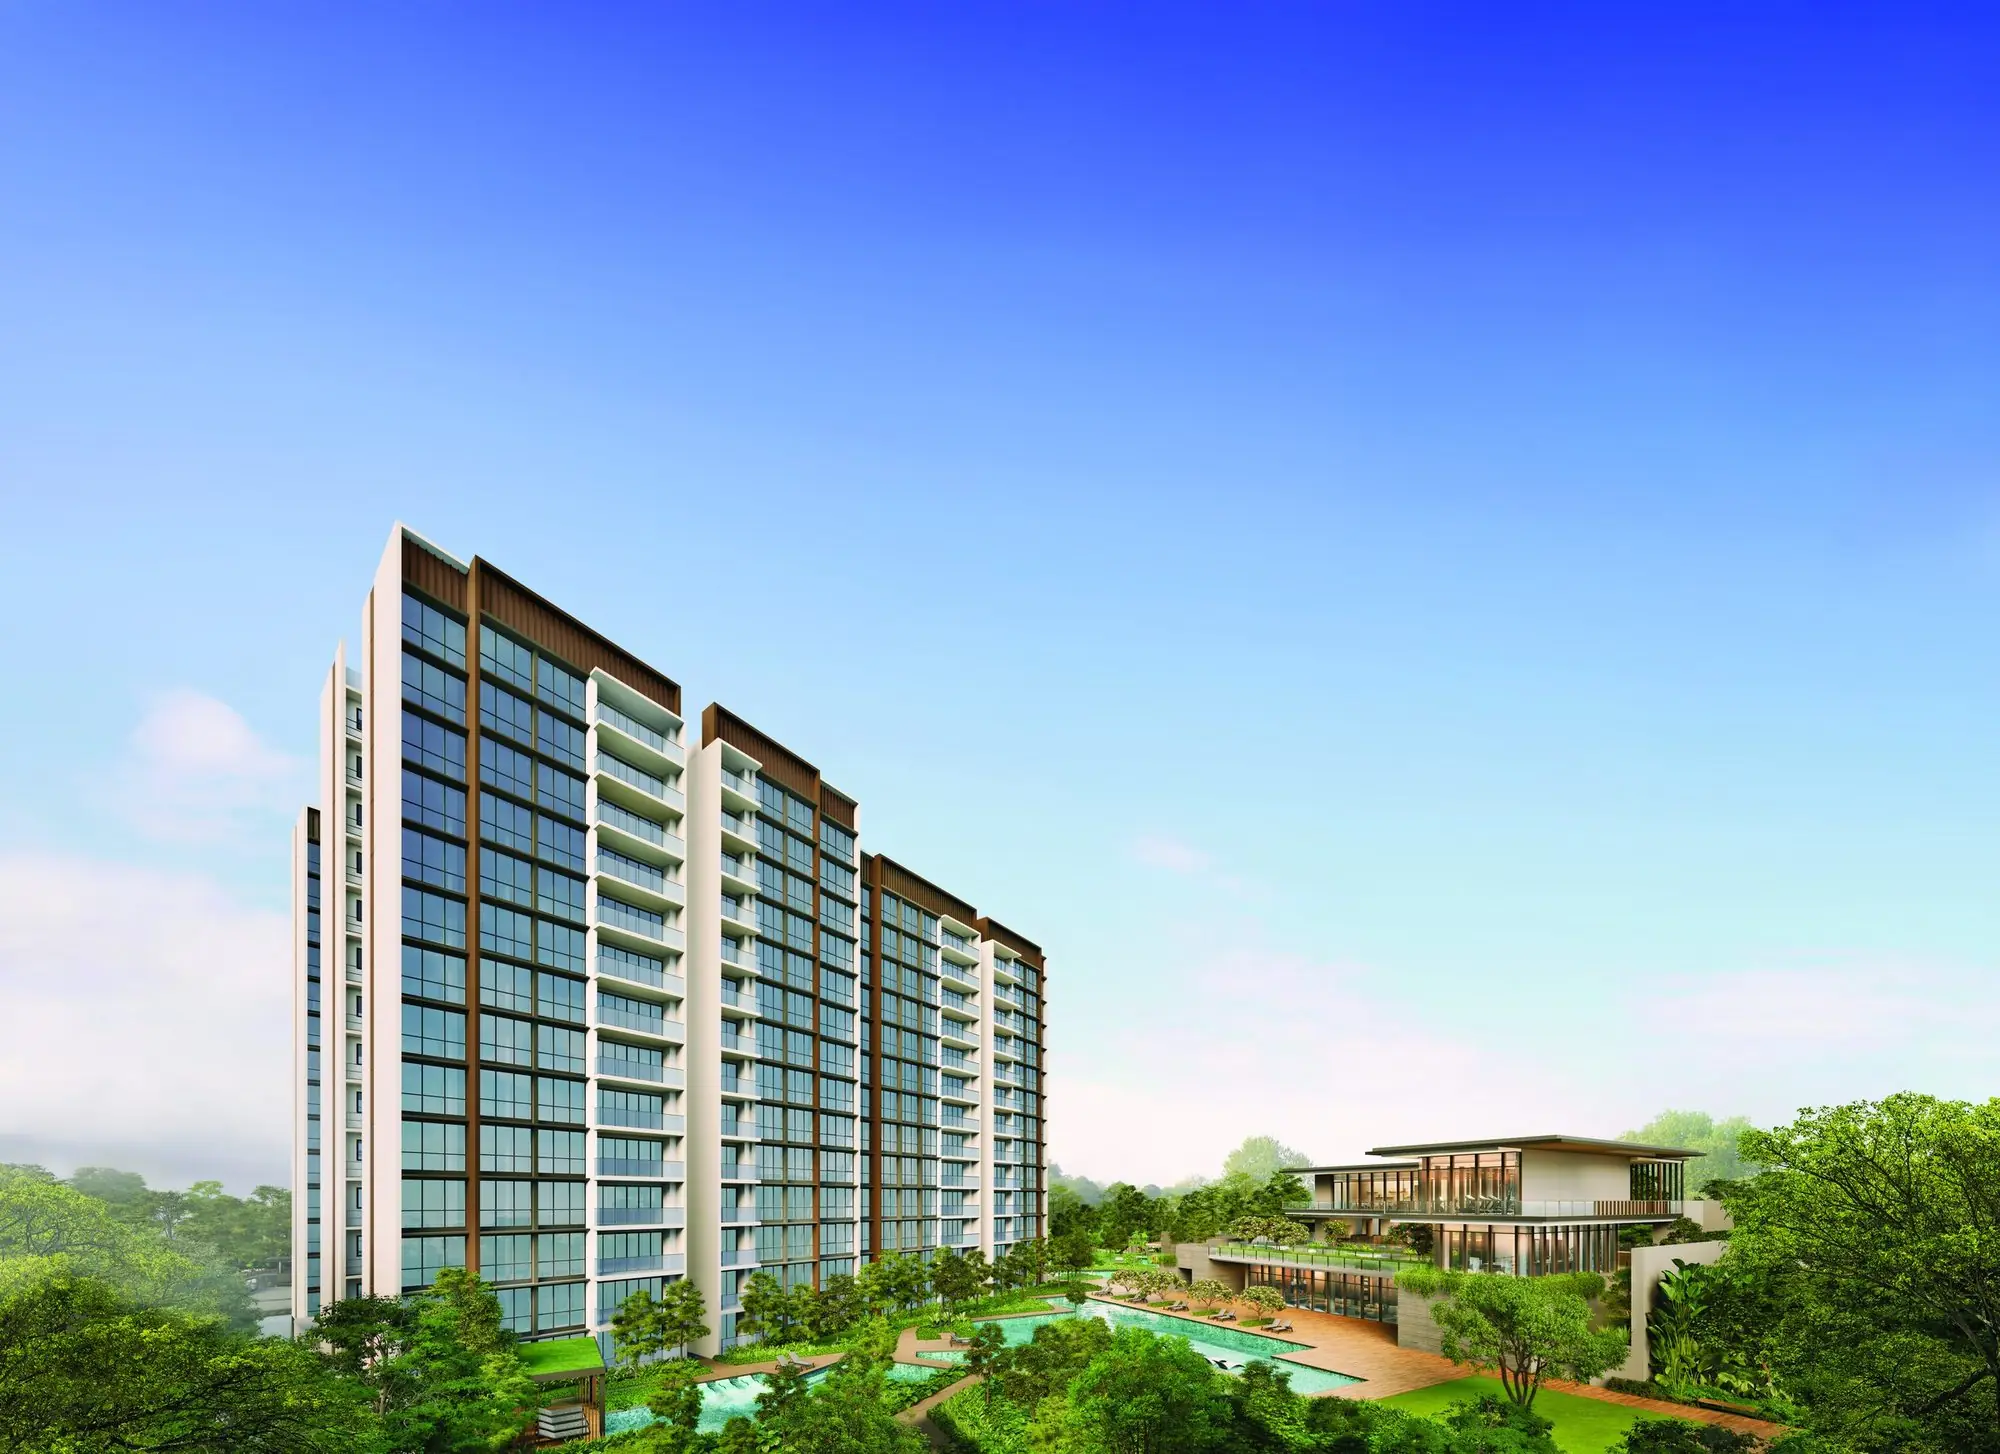
Tampines West has become one of the few places in Singapore where a new executive condominium and a new private condominium sit side by side, share an MRT station, and target the same upgrader. Rivelle is the EC, at Tampines Street 95. Pinery Residences is the private condominium integrated with Pinery Mall and the Tampines West station. A few hundred metres separate them.
That makes the pair a clean test of a question every EC-eligible household asks: what does the EC discount actually buy, and what does it cost? This article goes through the four differences that matter, then works a household example with real rules and rounded numbers. The private condo figures are marked "to be confirmed" because this site verifies developer data for Rivelle only; for Pinery Residences, check the developer's current price list.
Difference 1: who can buy
Rivelle is an EC. Buyers must form a family nucleus with at least one Singapore citizen and one citizen or permanent resident, have a combined household income of no more than S$16,000 a month, have no private property interest in the preceding 30 months, and have taken no more than two housing subsidies before. These rules are checked at booking and again at the Sale and Purchase stage. The full set, with the family nucleus schemes and worked examples, is in singaporeec.sg's EC eligibility guide.
Pinery Residences is private. Anyone can buy: singles, PRs, foreigners, companies. Foreigners pay Additional Buyer's Stamp Duty at 60 percent; Singapore citizens buying a second property pay 20 percent.
If you are not EC-eligible, the comparison ends here: Pinery Residences, or another private condo, is your option. If you are eligible, read on.
Difference 2: price
Rivelle's launch average was about S$1,893 psf (to be confirmed). Pinery Residences, as an integrated development above a mall and an MRT station, launched at a materially higher level, with reports in the region of S$2,100 to S$2,300 psf (to be confirmed). Take a 1,044 sqft four-bedroom as the comparison:
- Rivelle Type D1, 1,044 sqft at about S$1,893 psf: roughly S$1.98 million.
- A comparable four-bedroom at a private condo at S$2,200 psf: roughly S$2.30 million.
The gap on that unit is about S$320,000, or 16 percent. On a three-bedroom the gap is smaller in dollars but similar in percentage.
Two adjustments. First, Rivelle's D1 includes a 6 sqm balcony in its area; private condos also include balconies, so like for like. Second, EC buyers who are first-timers may receive the CPF Family Grant (up to S$30,000) and Half-Housing Grant, which widens the gap further; private buyers get nothing.
Difference 3: restrictions
This is what the discount pays for.
Minimum occupation period. Rivelle owners must live in the unit for five years from TOP before selling or renting out the whole unit. TOP is expected by 30 June 2030, so the MOP runs to around mid-2035. During that time the unit cannot be sold, and it cannot be rented out whole (renting a room is allowed after owners move in).
Resale buyer pool for years five to ten. From MOP until the tenth year after TOP, an EC can be sold only to Singapore citizens and permanent residents. Only from year ten (around 2040) is Rivelle fully privatised and sellable to foreigners.
Pinery Residences has none of these. The only hold-period cost is Seller's Stamp Duty, which falls to zero after three years. An owner can rent it out from day one.
For a family that intends to live in the unit for ten years, the restrictions cost nothing. For a family that might need to relocate, downsize or cash out within five years of TOP, they are a hard constraint.
Difference 4: financing
EC purchases from the developer are subject to the 30 percent Mortgage Servicing Ratio as well as the 55 percent Total Debt Servicing Ratio. Private condos face only TDSR. In practice, for a household at the EC income ceiling, MSR is the binding limit: at S$16,000 a month, MSR caps the monthly instalment at S$4,800, which at the 4 percent stress rate over 30 years supports a loan of about S$1.0 million. That is enough for 75 percent of a S$1.34 million purchase, not of a S$1.98 million one, which is why many EC buyers at the ceiling use the deferred payment scheme, a longer tenure, or cash and CPF beyond the minimum.
A private buyer with the same income is assessed at TDSR only: S$8,800 a month supports a loan of about S$1.84 million at the stress rate, which comfortably covers 75 percent of S$2.3 million. The private buyer's constraint is the downpayment and stamp duty, not the loan.
A worked example
Take a household of two Singapore citizens, first-timers, combined income S$15,000 a month, no other debts, S$200,000 in CPF Ordinary Account, S$150,000 cash. They want a four-bedroom in Tampines West.
Rivelle D1 at S$1.98 million (illustrative).
- 75 percent loan: S$1.485 million. MSR at 4 percent stress, 30 years: S$4,500 a month supports about S$943,000. Shortfall of about S$540,000 against the 75 percent loan.
- Realistic structure: 55 percent loan (about S$1.09 million, still above MSR by a margin that a bank may cover with a slightly longer tenure if ages allow) and 45 percent in cash and CPF, roughly S$890,000. With the deferred payment scheme, the loan is taken only at TOP in 2030, by which time income and CPF balances have grown.
- Grants: Family Grant S$20,000 at this income band (to be confirmed against HDB's current table).
- Buyer's Stamp Duty: about S$64,000.
- Verdict: tight at booking, workable with DPS and a plan to clear the cash gap by TOP, and the unit is theirs with no competition from investors or foreigners.
Private four-bedroom at S$2.30 million (illustrative).
- 75 percent loan: S$1.725 million. TDSR at stress: S$8,250 a month supports about S$1.73 million. Just passes.
- Downpayment 25 percent: S$575,000 (5 percent cash minimum S$115,000; balance CPF and cash). The household has S$350,000, so a shortfall of about S$225,000 before stamp duty.
- Buyer's Stamp Duty: about S$80,000. No grants.
- Verdict: not affordable for this household without an additional S$300,000, even though the loan passes.
The example is deliberately simple and uses rounded figures; the calculator lets you run your own. The point it illustrates is general: for an eligible household at the ceiling, the EC's binding constraint is MSR on the loan, while the private condo's binding constraint is cash for the downpayment, and the EC route is the one that closes.
When Pinery Residences is the right answer
- You are above the income ceiling, or your household composition does not form an EC family nucleus.
- You might need to sell or rent out within five years of TOP.
- You already own private property and are not willing to dispose of it 30 months before an EC booking.
- You want the convenience of living above the mall and the station, which has a value of its own for some households.
When Rivelle (or the next EC) is the right answer
- You are eligible and plan to stay ten years.
- The S$300,000-plus gap on a four-bedroom is the difference between buying and not buying.
- You are a first-timer and the grants apply.
Rivelle itself is sold out, so for most readers the live version of this choice is between Pinery Residences and the ECs now launching. Those are listed, with their status, on the other EC launches section of this site, fed from singaporeec.sg. The comparison above holds for any of them: adjust the psf and the MRT distance, and the logic is the same.